The Federal Government has formally concluded the financing arrangements for the N728.9 billion Series 2 power sector bond, taking its total debt-settlement issuances to about N1.23 trillion in nine months as it moves to restore liquidity and investor confidence across Nigeria’s electricity market.
The Series 2 bond is designed to settle part of the Federal Government’s estimated N4 trillion outstanding obligations to the electricity market, particularly verified debts owed to electricity generation companies (Gencos).
The financing documents were signed in Abuja on Monday, following approval of the Series 2 Tranche B issuance and the earlier completion of Series 2 Tranche A.
The latest transaction represents a major step in the government’s Presidential Power Sector Debt Reduction Programme (PPSDRP), but officials stressed that clearing historical debt alone will not resolve the structural weaknesses that continue to generate new liabilities across the electricity value chain.
Oyedele: Debt settlement must be backed by reforms
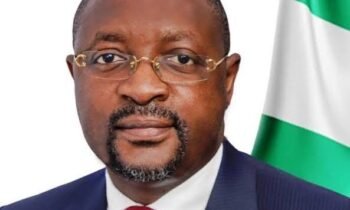
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, said the N728.9 billion transaction must be accompanied by stronger market discipline and reforms capable of preventing another accumulation of unpaid obligations.
The bond comprises N402 billion in cash bonds raised through the capital market and N326.9 billion in non-cash bonds allocated to participating Gencos.
According to Oyedele, the accumulated liabilities have weakened liquidity, constrained investment and damaged confidence among participants in the electricity market.
He said the government was determined to settle legitimate legacy obligations through a structured and transparent financing framework while simultaneously addressing the factors responsible for the emergence of fresh debt.
“The bond programme cannot stand alone. It must be accompanied by stronger market discipline, improved revenue assurance, reduction in technical and commercial losses, greater efficiency and accountability across the electricity ecosystem,” Oyedele said.
He said the government’s use of domestic capital markets demonstrated the capacity of Nigeria’s financial system to mobilise long-term capital for major economic interventions.
But the minister said the ultimate test of the programme would not be the amount of debt refinanced.
It would be whether the intervention produces an electricity market capable of paying its obligations, attracting investment and supplying more reliable power to households and businesses without repeated government bailouts.
Two issuances raise N1.23 trillion
The latest transaction brings the first phase of the government’s power-sector debt programme to N1.23 trillion.
CardinalStone Partners Managing Director, Michael Nwezi, said Series 1 raised N501 billion and closed in January 2026, while Series 2 raised approximately N729 billion.
Together, the two issuances raised about N1.23 trillion within nine months.
Nwezi described the first issuance as an important test of investor appetite for a structured power-sector instrument, given the longstanding financial challenges confronting the electricity industry.
He said the stronger performance of Series 2 demonstrated increased market confidence in the programme and its repayment framework.
The transaction attracted pension fund administrators, banks, sovereign wealth funds, asset managers and other institutional and retail investors.
Nwezi said the response showed that domestic capital was available for transformational projects where investors had adequate visibility, transparency and confidence in the underlying structure.
He said work would now commence on the second phase of the broader N4 trillion debt-settlement programme.
NBET: Debt has constrained generation investment
The Chief Executive Officer of Nigerian Bulk Electricity Trading Plc (NBET), Akin Odeyemi, described the Series 2 issuance as another milestone in efforts to resolve longstanding financial problems in Nigeria’s electricity supply industry.
Odeyemi said 11 Gencos participated in the Series 2 transaction, compared with eight under Series 1.
He said the broader participation reflected increased confidence in the debt-settlement framework and its ability to address verified obligations.
The accumulated debts, he noted, had affected the ability of market participants to meet their financial commitments and limited the capacity of generation companies to invest in additional electricity generation.
He said the programme should therefore be viewed as more than a debt repayment exercise.
It is also intended to restore liquidity, financial confidence and commercial sustainability across the electricity value chain.
Government warns that debt clearance is not power-sector reform
The Special Adviser to the President on Power, Dr Lanre Babalola, echoed the warning that settling legacy obligations must not be mistaken for comprehensive reform of the electricity industry.
He said Nigeria could not build a financially viable electricity market while carrying unresolved debts from the past.
But he added that resolving those debts would not prevent new liabilities unless the structural causes of poor market liquidity were addressed.
The government, he said, must improve payment and revenue collection, reduce technical, commercial and collection losses, accelerate metering and move tariffs progressively towards efficient cost recovery while protecting vulnerable consumers.
“The objective is ultimately a power sector that can pay its bills, attract investment, and expand reliable electricity supply without requiring government financial intervention,” Babalola said.
BPE: Commercial discipline must follow debt settlement
The Director-General of the Bureau of Public Enterprises (BPE), Ayodeji Gbeleyi, said the Series 2 transaction would help address verified legacy obligations owed to Gencos and restore liquidity to the market.
He also highlighted the successful payment of the first principal component of the Series 1 bond, which fell due in July 2026, as evidence of the government’s commitment to meeting its obligations under the programme.
Gbeleyi said the intervention was intended to create the financial conditions for a healthier electricity market rather than merely clear historical liabilities.
He said complementary measures were being implemented in the distribution segment to improve metering, revenue assurance and network performance while reducing aggregate technical, commercial and collection losses.
Gencos demand performance in return for liquidity
Representing the generation companies, Sahara Group Chief Executive Officer, Kola Adesina, described the bond programme as an important confidence-building measure.
Adesina said the government’s intervention was helping to restore liquidity and rebuild confidence from gas suppliers and generation companies to transmission and distribution operators.
But he said the industry’s response must now be improved performance.
“Improved liquidity must translate into greater generation availability, stronger networks, reduced losses, improved collections, increased investment, and ultimately more reliable electricity for Nigerian homes and businesses,” he said.
He warned that government intervention could not substitute for commercial discipline.
According to him, the long-term sustainability of Nigeria’s electricity market depends on accountability, cost-reflective economics, respect for contracts and a system in which every participant meets its financial obligations.
The bigger test: Can Nigeria stop the debt cycle?
The N1.23 trillion raised so far represents a significant financial intervention, but it does not by itself resolve the fundamental weakness in Nigeria’s electricity market.
The recurring accumulation of unpaid obligations has historically reflected a combination of inadequate revenue collection, electricity losses, weak payment discipline, insufficient tariffs, liquidity constraints and inefficiencies across the value chain.
Clearing the existing debt can provide a financial reset.
But without improvements in distribution company collections, metering, loss reduction, transmission reliability, gas supply and tariff economics, another debt overhang could eventually emerge.
For investors, the critical question is therefore what happens after the bond proceeds are deployed.
For Gencos, improved liquidity should support greater operational investment and generation availability.
For Discos, the pressure will increase to collect more of the value of electricity supplied.
For government, the challenge will be to gradually reduce its role as the industry’s financial backstop.
And for consumers, the ultimate measure remains simple: more reliable electricity and fewer disruptions at a cost that households and businesses can afford.
The success of the power bond will therefore depend less on the size of the cheque issued and more on whether Nigeria can finally break the cycle of unpaid electricity bills, accumulating sector debt and repeated government intervention.