



NMDPRA’s Revision 2 seeks to reduce gas transportation imbalances, improve market transparency and strengthen investor confidence. Its success will depend on pipeline capacity, regulatory enforcement and the ability to convert Nigeria’s vast gas resources into reliable supplies for industry, power generation and regional markets.
Nigeria’s decision to revise its Gas Transportation Network Code signals a renewed effort to address one of the structural weaknesses holding back its natural gas industry: the gap between the country’s substantial gas resources and its capacity to transport and deliver the commodity reliably to paying customers.
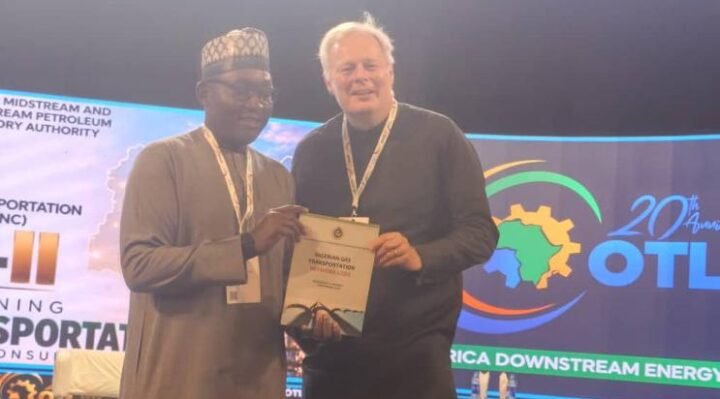
The Nigerian Midstream and Downstream Petroleum Regulatory Authority (NMDPRA) unveiled Revision 2 of the Nigerian Gas Transportation Network Code at the 20th edition of OTL Africa Downstream Energy Week 2026 in Lagos, introducing updated rules intended to improve gas measurement, transportation nominations, network coordination and operational transparency.
Rabiu Umar, chief executive of the NMDPRA, announced the revision on Monday, saying participation in the network had increased since the introduction of Revision 1, while imbalances on the western gas network had declined by 30 per cent.
The reported reduction suggests that clearer transportation rules and better coordination can improve the management of existing infrastructure. But the wider economic significance of Revision 2 will depend on whether the regulatory changes translate into more dependable gas deliveries, lower transaction costs and greater investment in Nigeria’s gas value chain.
For Nigeria, the stakes extend beyond the petroleum industry. Gas transportation efficiency affects electricity generation, industrial productivity, manufacturing costs, energy security and the country’s ambitions to become a major supplier to African energy markets.
Nigeria’s gas investment challenge goes beyond reserves
Nigeria possesses substantial natural gas resources, but resource abundance alone does not guarantee economic value. Gas must be produced, processed, transported and delivered at commercially viable prices before it can support industrial growth or generate export revenue.
The transportation network is therefore a critical link between upstream gas producers and downstream consumers, including power plants, fertiliser manufacturers, petrochemical companies, industrial facilities and gas distributors.
Where pipeline access is uncertain, transportation arrangements are unpredictable or measurement disputes persist, producers face difficulties securing buyers, while consumers struggle to plan operations and manage supply risks.
The revised network code seeks to improve this operating environment by establishing clearer procedures for measuring gas volumes, submitting nominations for transportation and coordinating deliveries through the network.
These measures could reduce disputes between shippers and network operators, improve capacity planning and strengthen accountability for differences between nominated and delivered gas volumes.
The reported 30 per cent reduction in imbalances on the western network following Revision 1 offers an initial indication of the potential benefits of better network management. However, the figure alone does not establish the scale of additional gas delivered, the financial savings achieved or the extent to which supply reliability has improved for industrial consumers.
For investors, those commercial outcomes matter more than the publication of a revised regulatory document.
Why Revision 2 matters for Nigeria’s power sector
The implications for electricity generation could be significant if the revised code improves the reliability of gas deliveries to power plants.
Gas-fired generation remains an important component of Nigeria’s electricity supply. However, inadequate gas availability, transportation constraints, infrastructure failures and payment challenges have repeatedly complicated the relationship between gas suppliers and electricity generators.
A more transparent transportation framework could help power plants secure and schedule deliveries more effectively, provided sufficient gas production and pipeline capacity are available.
Better coordination could also improve the identification of bottlenecks, clarify the responsibilities of network participants and reduce avoidable operational losses.
But the revised code cannot, on its own, resolve Nigeria’s electricity crisis.
Power plants still require adequate gas supplies, functioning equipment, reliable transmission infrastructure and commercially sustainable arrangements across the electricity value chain. Gas producers also need confidence that their customers can pay for delivered supplies.
Consequently, the impact of Revision 2 on electricity generation will depend on whether the new rules are accompanied by investment in pipelines and processing facilities, improvements in the financial position of gas buyers and effective coordination between the gas and power industries.
If these conditions are met, more reliable gas transportation could support generation availability, reduce operational uncertainty and improve electricity supply to businesses and households.
If they are not, improved transportation procedures may produce administrative efficiencies without delivering a commensurate improvement in power generation.
Manufacturing and industrial competitiveness at stake
The implications extend to manufacturers that depend on gas as both a fuel and a feedstock.
Industries such as fertiliser production, cement manufacturing, steel processing, glassmaking and petrochemicals require dependable energy supplies to maintain production schedules and control operating costs.
Unreliable gas deliveries can force industrial users to reduce output, switch to more expensive fuels or operate below installed capacity. These adjustments increase costs and can weaken the competitiveness of locally manufactured products.
A more predictable transportation regime could help industrial consumers negotiate supply arrangements, plan production and assess the commercial viability of new gas-dependent investments.
It could also strengthen the investment case for gas processing, compressed natural gas, liquefied petroleum gas infrastructure and other downstream applications, although each segment faces distinct infrastructure, pricing and demand constraints.
For Nigeria, the potential economic benefit lies in using gas to support value addition rather than relying exclusively on the sale of unprocessed hydrocarbons.
More dependable supplies could support industrial expansion, employment, import substitution and the development of domestic supply chains. The scale of those benefits, however, will depend on the cost of gas, the availability of financing and the ability of industrial customers to secure long-term supplies.
Investment implications: regulatory certainty must become commercial certainty
Olu Verheijen, Special Adviser to the President on Energy (Oil and Gas), underscored the importance of predictable regulation in attracting investment into Nigeria’s gas infrastructure.
Represented at the event by Eriye Onagoruwa, team lead in the Office of the Special Adviser to the President on Energy, Verheijen highlighted the role of natural gas in power generation, industrial development and transportation.
The emphasis on regulatory certainty reflects a central consideration for investors: infrastructure projects require confidence that market rules will be clear, consistently applied and commercially sustainable over the life of an investment.
Gas pipelines and processing facilities typically require substantial upfront capital and long investment horizons. Investors must therefore assess not only the demand for gas but also access arrangements, transportation charges, tariff predictability, payment security and the treatment of contractual disputes.
Revision 2 could help reduce some regulatory and operational uncertainties by clarifying how participants use the network.
Nevertheless, investment decisions will depend on the credibility of implementation. Rules that are poorly enforced, applied inconsistently or undermined by inadequate infrastructure will offer limited protection against commercial risk.
Investors will also need clarity on available transportation capacity, congestion management, third-party access, measurement standards and the allocation of responsibility when nominated volumes are not delivered.
The critical test is whether Nigeria can move from regulatory clarity on paper to predictable commercial performance in practice.
NNPC highlights infrastructure and regional cooperation
Mumuni Dagazau, Executive Vice-President, Downstream, Nigerian National Petroleum Company Limited (NNPC Ltd.), called for greater investment in gas infrastructure, stronger industry coordination and deeper regional cooperation.
The emphasis on infrastructure reflects the need to connect gas-producing areas with domestic demand centres and export markets.
Pipelines, gas processing plants, compression facilities and distribution networks are essential to moving supplies from production sites to power plants, factories and regional customers. Where these links are inadequate, additional production may fail to generate its full economic potential.
Infrastructure investment could also support a broader range of commercial participants, including independent producers, pipeline operators, gas marketers and industrial buyers.
For NNPC Ltd. and other market participants, improved transportation arrangements could help strengthen coordination across the value chain. The benefits would depend on transparent access conditions and a framework that allows commercially viable projects to compete for capacity.
Regional cooperation adds another dimension. Cross-border gas trade requires not only physical connections but also compatible regulations, dependable supply contracts, payment arrangements and confidence among participating countries.
Nigeria’s ability to provide reliable supplies will therefore influence both its domestic industrial ambitions and its prospects for expanding gas exports across West Africa.
Implications for Africa: a stronger foundation for regional gas trade
For Africa, Nigeria’s revised gas network code has significance beyond its domestic market.
Nigeria is an important participant in West African energy supply, and its gas infrastructure can contribute to regional electricity generation and industrial development. More efficient transportation arrangements could help improve the commercial foundations for cross-border gas trade.
The West African Gas Pipeline provides an existing regional framework for transporting Nigerian gas to neighbouring markets, including Benin, Togo and Ghana. However, the extent to which improved domestic network operations translate into greater regional supply will depend on production availability, pipeline capacity, contractual commitments and demand in destination markets.
A more predictable Nigerian gas market could make it easier for producers and buyers to evaluate long-term supply agreements and infrastructure investments.
It could also encourage regional policymakers to strengthen coordination around gas transportation standards, market access and payment security.
For countries seeking to expand electricity generation or develop gas-based industries, reliable supplies from Nigeria could offer an additional energy source. For Nigerian producers, regional demand could broaden the customer base and create opportunities to monetise gas that might otherwise remain commercially stranded.
However, the benefits will not be automatic. Cross-border infrastructure is capital-intensive, and regional markets face their own challenges involving affordability, foreign-exchange availability, creditworthiness and competing energy sources.
Revision 2 should therefore be viewed as a potential building block for regional integration rather than evidence that a more integrated African gas market has already emerged.
Global implications: Nigeria’s place in a changing gas market
The international significance of Nigeria’s gas reforms lies in the competition for capital, markets and reliable energy supplies.
Global gas markets are shaped by changing demand, geopolitical risks, infrastructure constraints, price volatility and the expansion of liquefied natural gas (LNG) trade. Producers must demonstrate that they can supply gas reliably and under commercially credible arrangements if they are to attract long-term buyers and investors.
Nigeria already participates in international gas markets through LNG exports. Improving the domestic transportation system could support the wider development of its gas industry by strengthening links between production, processing and domestic consumption.
More efficient infrastructure could also help investors evaluate projects that serve both domestic and export markets, where commercially and technically feasible.
Yet a revised network code should not be confused with an immediate increase in LNG exports or a guarantee of additional foreign investment. Those outcomes would require adequate production, processing capacity, infrastructure, financing and competitive commercial terms.
Nigeria must also balance its export ambitions against domestic energy needs. Reliable gas supplies to power plants and industrial consumers can support economic growth, while exports generate foreign exchange and government revenue. The policy challenge is to establish commercially sustainable arrangements that allow both objectives to be pursued without creating avoidable supply constraints.
For international investors, the relevant question is whether Nigeria can combine regulatory predictability with dependable infrastructure, enforceable contracts and a credible framework for resolving disputes.
OTL Africa’s wider message on energy security
The discussions at the 20th edition of OTL Africa Downstream Energy Week reflect a broader debate about the infrastructure needed to support energy security and economic development across Africa.
Tunji Oyebanji, Chairman of the OTL Africa Downstream Advisory Board, highlighted the importance of infrastructure development, efficient logistics and commercial partnerships among African countries.
Held under the theme “Secure Energy, Shared Prosperity,” the 2026 event brought together regulators, policymakers, operators and investors to consider developments and investment opportunities across the continent’s downstream energy industry.
The discussions point to a common challenge: energy security depends not simply on the availability of resources but also on the institutions, infrastructure and commercial arrangements that make those resources accessible to consumers.
For gas markets, this means aligning production with transportation capacity, ensuring transparent access to networks and building confidence in contractual performance.
What investors should watch next
The success of Revision 2 will ultimately be measured by operational and commercial outcomes rather than regulatory announcements alone.
Investors, gas producers, power generators and industrial consumers should watch several indicators:
- Network imbalances: Whether the reported reduction on the western network is sustained and extended to other parts of the transportation system.
- Gas delivery reliability: Whether actual deliveries increasingly match nominated volumes and contractual commitments.
- Infrastructure utilisation: Whether existing pipelines and processing facilities can transport more commercially available gas without persistent bottlenecks.
- Investment commitments: Whether clearer operating rules translate into financing decisions for new pipelines, processing facilities and distribution networks.
- Industrial consumption: Whether manufacturers and power plants receive more reliable supplies at commercially viable prices.
- Regional trade: Whether improved domestic transportation supports dependable cross-border deliveries and stronger gas supply agreements.
- Regulatory enforcement: Whether network access, measurement, nomination and dispute-resolution rules are applied transparently and consistently.
Publishing the revised code is an important regulatory step, but its economic value will depend on measurable improvements across these indicators.
Conclusion: Nigeria must turn gas regulation into economic value
Revision 2 of the Nigerian Gas Transportation Network Code addresses an important part of the infrastructure and regulatory framework needed to expand gas utilisation in Nigeria.
Clearer rules for measurement, nominations and transportation could reduce operational uncertainty, improve coordination and strengthen the investment case for parts of the gas value chain.
For Nigeria, the potential rewards include more reliable industrial energy supplies, stronger support for gas-fired electricity generation, greater opportunities for domestic value addition and improved prospects for attracting infrastructure capital.
For Africa, more efficient Nigerian gas transportation could support regional energy trade and strengthen links between producers and consumers. For the global oil and gas community, the reform offers a test of Nigeria’s ability to turn regulatory changes into a more predictable and commercially attractive market.
But the decisive factor will be implementation. Without adequate infrastructure, reliable production, payment discipline and consistent enforcement, better rules alone cannot guarantee better supplies.
Nigeria’s real challenge is not merely to regulate gas transportation more effectively, but to ensure that its gas resources are delivered reliably, priced competitively and converted into measurable economic value.